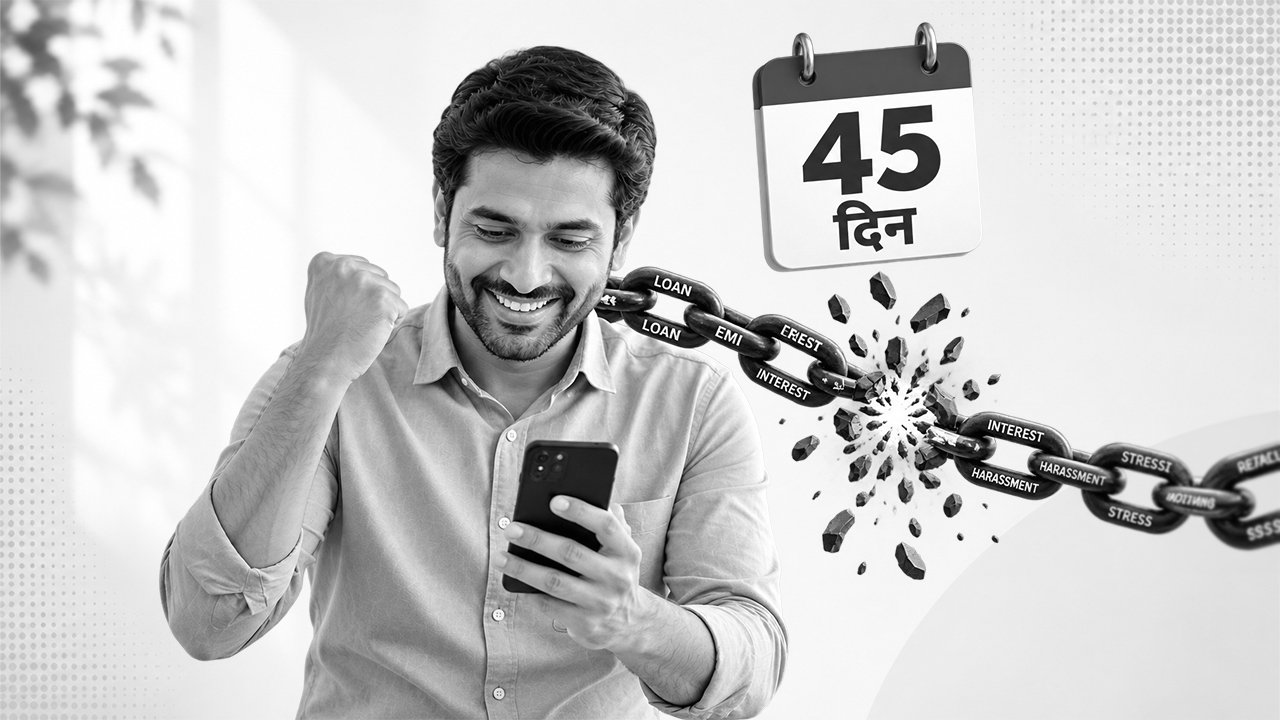
Zero Debt Stress in 45 Days: What Can Really Happen?
Can debt be settled within 45 days? Yes, it can be possible for eligible borrowers.
Settle My Loan’s Break the Debt Chain (BTDC) – 45 Days Settlement Challenge helps eligible borrowers take structured action towards resolving unsecured debt. SML has documented cases of negotiated settlements achieved within 45 days, including cases settled in as little as 12 days.
However, 45 days is not guaranteed. Timelines and settlement terms depend on the borrower’s financial circumstances, account status, documentation, eligibility, creditor policies and negotiations.
The goal is to help eligible borrowers move from overwhelming debt towards a clear path to resolution, with settlement within 45 days being a favourable outcome where circumstances allow.
Key Takeaways
- Debt settlement can be achieved within 45 days in eligible cases, depending on the borrower’s circumstances and creditor negotiations.
- SML has documented cases where settlements were secured well within the 45-day period.
- The process begins with understanding the borrower’s financial situation, assessing eligibility and organising the required documentation.
- Structured creditor communication and negotiation can help borrowers work towards mutually agreed settlement terms.
- Support can also help address persistent collection-related pressure and establish a more structured communication process with creditors, where applicable.
- Even when a settlement takes longer than 45 days, the initial period can create meaningful progress through assessment, documentation, negotiation and resolution planning.
- The 45-day challenge is a targeted resolution window, not a guarantee of settlement.
What Does “Zero Debt Stress” Really Mean?
Debt stress goes beyond the amount owed. It can involve EMI worries, multiple repayment dates, repeated collection calls, household expenses and uncertainty about what to do next.
Zero debt stress does not mean that debt automatically disappears within 45 days. It means reducing the uncertainty and pressure around debt by taking informed steps towards resolution.
For eligible borrowers, this can involve assessing their financial position, understanding their debt obligations and working through the appropriate resolution process with creditors.
Why Borrowers Get Trapped in the Debt Cycle
Financial distress can arise even when borrowing initially seemed manageable. Job loss, business slowdown, medical expenses, family emergencies, or rising household costs can disrupt repayment plans.
When one repayment becomes difficult, borrowers may take on additional credit to manage immediate obligations, creating a cycle:
- Personal loan EMIs become difficult to manage.
- Credit cards are used for everyday expenses.
- Another loan is taken to manage existing debt.
- Interest and repayment obligations continue to grow.
- Multiple creditors demand repayment, increasing financial pressure.
This can lead to new borrowing being used to manage existing debt.
Breaking the debt cycle requires action, not another loan.
Can 45 Days Really Make a Difference?
Yes. For eligible borrowers, 45 days can be enough to achieve a negotiated debt settlement in some cases. SML’s 45 Days Settlement Challenge provides a structured approach to debt resolution, including:
- Debt Assessment: Reviewing financial circumstances, outstanding obligations, account status and repayment history.
- Eligibility & Documentation: Assessing suitability and organising relevant financial and account documents.
- Creditor Communication & Negotiation: Communicating with creditors and working towards mutually acceptable settlement terms.
- Resolution: Completing the required formalities once settlement terms are agreed.
Some eligible borrowers may reach settlement within 45 days, while others may require more time. Every case is different, and creditors ultimately determine whether and when a settlement can be reached.
Real case study
Surendar Balasubramaniam enrolled with Settle My Loan amid financial and medical hardships and nearly six months of missed EMIs. SML supported his case through hardship-based negotiation and legal assistance. Within 12 days, the creditor agreed to a settlement at 24% of the outstanding amount payable, with the documentation reviewed by SML’s Advocate and Paralegal teams. His case demonstrates how structured debt resolution support can help eligible borrowers work towards a defined resolution.
Read full case study here
What If Settlement Doesn’t Happen Within 45 Days?
A successful debt-resolution journey does not have to be defined by a single deadline.
For some eligible borrowers, the best-case outcome may be a negotiated settlement within 45 days.
For others, the first 45 days can create important progress towards that outcome.
| What Can Happen | What It Means |
| Debt assessment | The borrower’s outstanding obligations and financial position are clearly evaluated. |
| Documentation organised | Required financial and account information is prepared for the resolution process. |
| Creditor communication begins | Structured communication can be initiated with relevant creditors. |
| Negotiations begin | Settlement possibilities can be explored based on the borrower’s circumstances. |
| Collection pressure addressed | Borrowers facing persistent collection-related concerns can receive structured support and guidance, where applicable. |
| Settlement achieved | Some eligible cases may reach a negotiated settlement within the 45-day period. |
| Resolution pathway established | Where settlement takes longer, the groundwork for continued negotiations can be established. |
The objective is progress towards resolution with settlement within 45 days representing the most favourable outcome where the circumstances allow it.
How Professional Debt Resolution Support Can Help
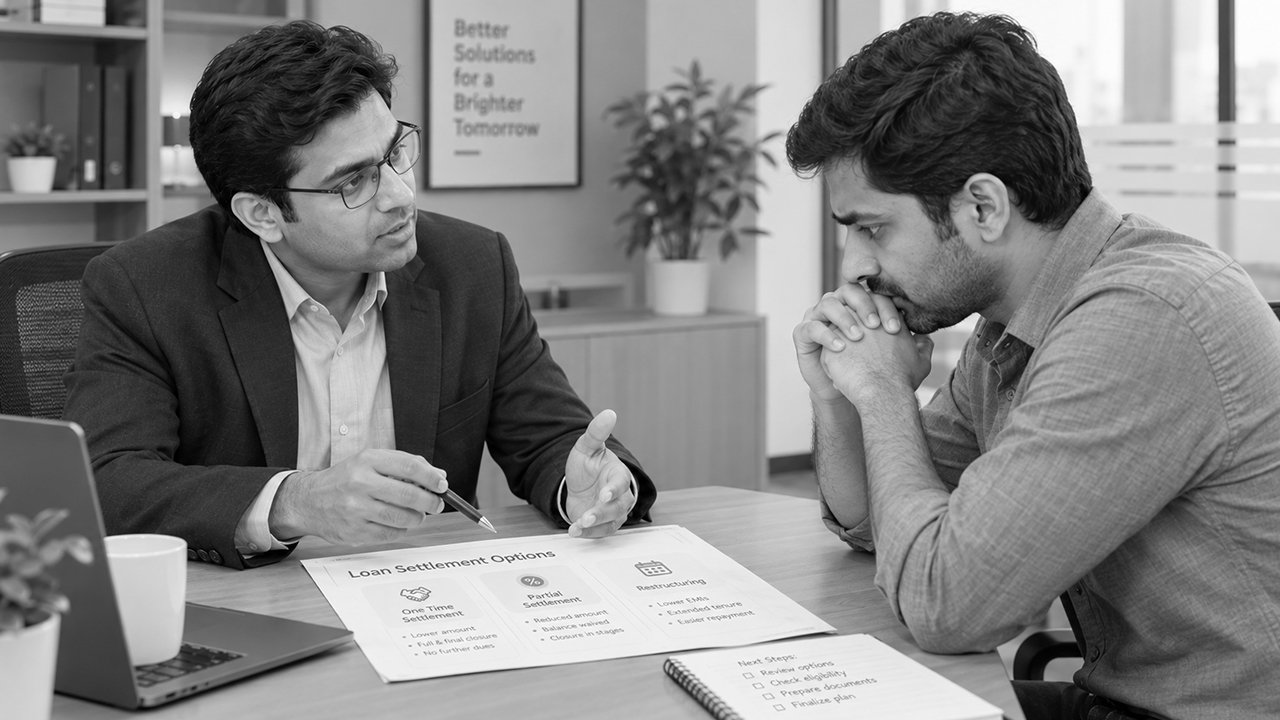
Managing multiple creditors, repayment demands and negotiations can be overwhelming during financial distress. Professional debt resolution support can help eligible borrowers navigate the process with greater structure and clarity.
This may include:
- Financial assessment and OTS evaluation
- Review of outstanding unsecured debt
- Documentation and creditor communication support
- Negotiation with creditors
- Legal assistance, where relevant
- Support with persistent collection-related concerns
- Guidance throughout the resolution process
The objective is to help eligible borrowers understand their options and work towards a practical, documented resolution based on mutually agreed terms with the creditor.
Life After Debt Resolution
Reaching a settlement is an important milestone, but financial recovery continues beyond debt resolution. Borrowers should focus on building healthier financial habits, such as:
- Building an emergency fund
- Avoiding unnecessary new borrowing
- Maintaining a realistic monthly budget
- Making future repayments on time
- Monitoring credit reports regularly
- Rebuilding responsible credit behaviour
A loan settlement may affect how an account is reported in the borrower’s credit history, so understanding the potential credit implications is important.
The goal after settlement is to build a stronger financial foundation and avoid falling back into the debt cycle.
Break the Debt Chain Starts with Taking Action
Debt can feel like a cycle with no clear way forward, but taking structured action can help change that.
The Break the Debt Chain – 45 Days Settlement Challenge gives eligible borrowers a structured opportunity to work towards resolving unsecured debt. For some, this can result in a negotiated settlement within 45 days, while documented SML cases show that resolution can sometimes happen sooner.
Where more time is needed, the first 45 days can help create clarity, begin creditor negotiations, address collection-related concerns, and establish a path towards resolution.
Outcomes depend on the borrower’s circumstances, eligibility, account status, documentation, creditor policies and negotiations.
Your 45 days can be the beginning of breaking the debt chain.
Break the Debt Chain with Settle My Loan
45 days can change the direction of your debt journey.
For some eligible borrowers, it may be enough to achieve a negotiated settlement.
For others, it can be the first 45 days of a structured path towards resolution.
Take the first step. Break the Debt Chain.
Terms and conditions apply. Settlement outcomes, timelines and savings vary based on individual circumstances, eligibility, account status, documentation, creditor policies and negotiations. The 45 Days Settlement Challenge does not guarantee settlement within 45 days.
Disclaimer: Participation, timelines and negotiation terms under the 45 Days Settlement Challenge are subject to eligibility, lender approval, and individual case circumstances. Terms and conditions apply
FAQ
Do Like and Share