Should You Hire a Loan Settlement Consultant? Benefits, Cons, and Costs Explained
Every year, thousands of Indian borrowers try to negotiate their loans directly with banks with almost all of them settling for far less savings than they could get. If you have been searching for whether a loan settlement consultant fee is worth it, you are already asking the right question. After all, banks in India have entire departments dedicated to loan settlement with scripts, policies, and multi-year experience.
This is exactly the moment most Indian borrowers start googling things like “how to settle my loan” or “can someone negotiate on my behalf?”
This article gives you a straight answer: what a consultant actually does, how much they charge, and whether the math works in your favour.
Let’s break it down honestly.
What Does a Loan Settlement Consultant Actually Do?
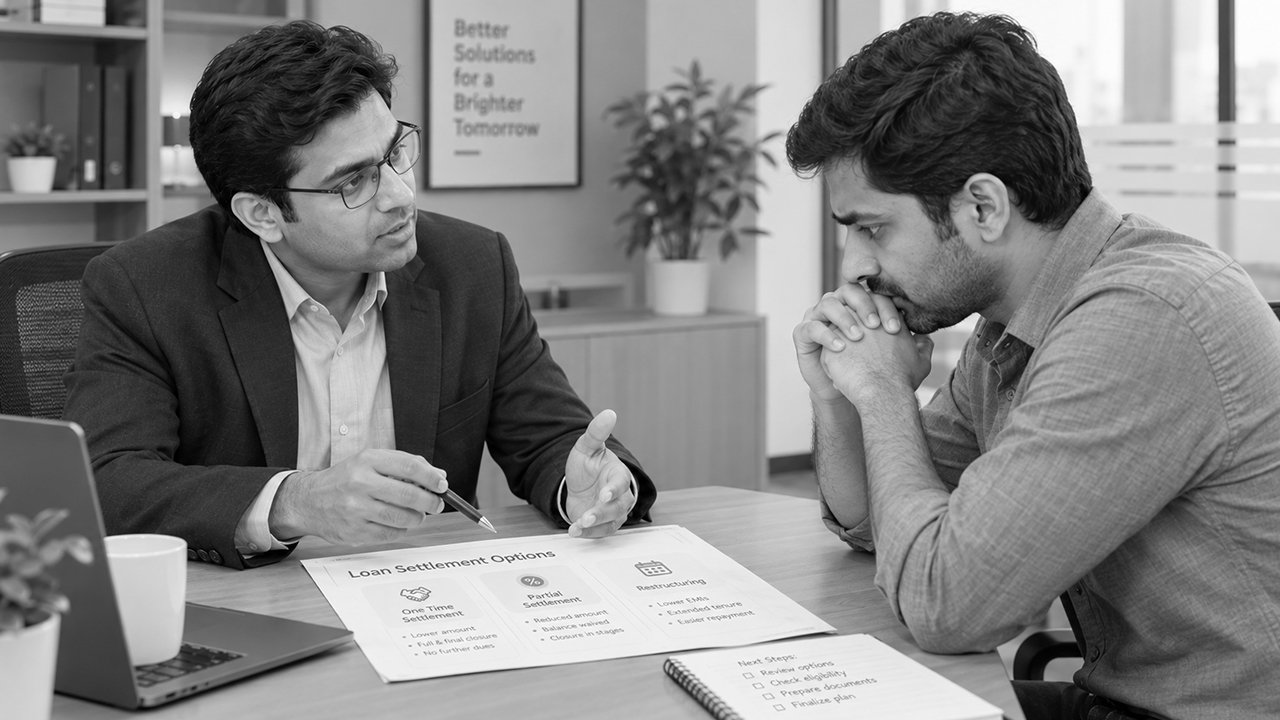
A loan settlement consultant (sometimes called a debt negotiator or a debt relief agency) is a trained professional or company. They review your financial situation, build a case for settlement and prepare all documentation. Then the consultant negotiates directly with your bank or NBFC to arrive at a reduced payoff amount.
When you walk into a bank to negotiate a settlement, you are sitting across from a team of trained recovery officers whose main responsibility is to extract as much lending amount as possible from borrowers. At such times, going in alone without knowing the bank’s internal policies, NPA norms, RBI guidelines, or settlement benchmarks is the speed ticket to loss.
A good consultant levels that playing field.
Key Benefits of Hiring a Debt Relief Agency or Consultant
The following are the top advantages of hiring a loan settlement consultant:
1. Full Information About Bank’s Policies
Banks do not advertise their settlement terms. They will not tell you upfront that they are willing to accept 50% of your outstanding as a One Time Settlement. An experienced consultant quickly assesses each lender’s preferences and identifies key leverage points.
This specialized knowledge can lead to substantial financial savings, often amounting to lakhs.
2. Less or No Harassment
One of the biggest debt relief agency benefits that mostly gets unnoticed is the mental relief. When you hire a debt negotiator, they take over all communication with your creditors. Calls at 7 AM, threatening messages or unannounced visits of recovery agents falls squarely under harassment as defined in the RBI’s official circular on recovery agent conduct.
3. Legal Protection Comes Bundled
If your lender has sent a legal notice or filed a recovery case, a good settlement company has in-house advocates to deal with. These advocates respond to those notices, handle arbitration, and protect you from wrongful recovery actions. By paying a legal settlement consultant fees, you are not just hiring a negotiator, you are getting legal cover.
4. Better Savings from Settlement vs. Individual
This is the most important point: savings from settlement vs. fees almost always favour the professional route.
Here is a simple example. Say you owe ₹10 lakhs on a personal loan. If you go to the bank yourself, you might manage to settle for ₹7.5 lakhs, if the bank agrees to engage at all. That is a saving of ₹2.5 lakhs.
Now if a consultant like Settle My Loan negotiates for you, the settlement could come down to ₹5 lakhs, saving you ₹5 lakhs. Their fee of 15% on the settled amount works out to ₹75,000. Your net savings is still ₹4.25 lakhs.
You paid ₹75,000. You saved ₹4.25 lakhs. That is an ROI of over 5x.
This is why debt settlement is worth it, especially when a professional is handling your case.
Cons of Hiring a Loan Settlement Consultant
We believe in giving you the full picture. So here are the genuine downsides of hiring a loan settlement agent:
1. Costs Money
Loan settlement consultant fees are real costs. Most agencies come with a monthly case management subscription plan of over ₹1,000 -₹2,999 depending on your debt size. There’s also the probability of additional charges like a success fee which are often hidden.
Now if you compare this to settling on your own with zero fees paid, yes, it is a better option for your finances. The question is always: how much more do you save because of the consultant?
2. Effect on the CIBIL Score
Whether you settle through a consultant or on your own, a loan settlement does mark your credit report as “Settled” instead of “Closed.” This stays on your CIBIL for up to 7 years and signals to future lenders that you did not repay a previous loan in full.
That said, this is an outcome of the settlement itself, not a consequence of hiring a consultant. In fact, consultants can help you explore options like OTS with Credit Clearance or Term Settlement with Credit Clearance, where the credit report gets updated to “NIL” after full payment, hence minimising the damage.
3. Not Every Case Qualifies
Settlement works best for unsecured debts including personal loans, credit cards, and unsecured business loans. If your loan is secured by property or a vehicle, settlement gets more complicated. A good consultant will tell you this upfront rather than taking your money and promising outcomes they cannot deliver.
Going it alone is not impossible, but the risks are high and the savings are usually far smaller than what a professional negotiator achieves for you.
The ROI Case: Does the Fee Pay for Itself?
Let us do this calculation one more time for a legal settlement consultant fee clearly:
Outstanding debt: ₹6 lakhs
| Scenario | Settlement Amount | Consultant Fee | Net Saving |
| Self-negotiation | ₹4.8 lakhs | Nil | ₹1.2 lakhs |
| With Settle My Loan | ₹3 lakhs | ~₹45,000 (15%) | ₹2.55 lakhs |
The consultant saves you ₹1.35 lakhs more, excluding their fee. For many clients, Settle My Loan’s team has achieved reductions of 60–70%, particularly through options like Reversal Settlement, where all interest and penalties are waived and borrowers only repay the principal.
How to Spot a Legitimate Loan Settlement Consultant?
A trustworthy company like Settle My Loan is ISO certified, operates with SEBI-regulated Escrow accounts for your savings, and gives you a legally binding agreement from day one.
Not every agency claiming to settle your loan is genuine. Watch out for these red flags:
- They ask for the full fee upfront before doing any work.
- They guarantee a specific CIBIL score improvement within 30 days.
- There is no written service agreement.
- They have no verifiable office address or registration.
- They avoid explaining the process clearly.
Hiring a loan settlement consultant makes strong financial sense. Ready to find out how much you could save? Settle My Loan offers a free consultation with no commitment. Share your loan details, and a specialist will tell you exactly what settlement options are available to you — and what you can realistically expect to save.