This Dussehra, Defeat Your Loan the Right Way With One Time Settlement
Quick Snapshot:
- The Core Issue: Like the multi-headed demon Ravana, unsecured debt constantly grows back through compound interest, bounce charges, and new penalties, trapping you in a cycle of fear and recovery harassment.
- The Solution: A One Time Settlement (OTS) is the ultimate financial weapon. It allows individuals facing genuine financial hardship to legally close their accounts for a fraction of the total outstanding amount.
- The Action Plan: This Dussehra, stop taking new loans to pay old EMIs. Partner with a professional loan settlement agency to settle your loan, reduce the harassment, negotiate with your banks, and reclaim your financial freedom.
Across India, towering effigies of Ravana will soon go up in flames, marking the joyous festival of Dussehra (Vijayadashami). It is a powerful, visual reminder that, no matter how massive or invincible evil appears, truth and righteousness always win.
But for millions of Indians, the most terrifying demon isn’t a mythological figure from the past. It is the real, daily nightmare of unpaid, unsecured loans, mounting credit card bills, and the relentless harassment inflicted by recovery agents.
When you are drowning in debt due to a sudden job loss, business failure, or medical emergency, the festive season can feel incredibly isolating. However, this Dussehra, you do not have to live in fear. It is time to stop running, face the problem, and defeat your loan the right way using a One Time Settlement (OTS).
The 10-Headed Demon: The Trap of Unsecured Loans
In the epic Ramayana, Ravana was nearly invincible because every time one of his heads was cut off, a new one instantly grew in its place. Unsecured debt works exactly the same way.
When you fall into financial hardship, the pressure to pay is immense. Out of pure panic, many borrowers take a new, high-interest loan from an instant app just to pay off an old personal loan EMI. By doing this, you are only cutting off one head.
Instantly, the debt grows back stronger. The banks apply massive bounce charges, late fees, and compound interest. Soon, the bank assigns third-party recovery agents, and the real psychological torture begins. These agents use abusive language, call your family members, and issue fake legal threats to break your confidence.
Expert Insight: The Reality of the Debt Trap
If you feel suffocated by your EMI burden, you are not alone. You are part of a growing national trend. According to the Reserve Bank of India’s Financial Stability Report (June 2026), Indian household debt has climbed to 45.5% of GDP. Non-housing retail loans such as personal loans and credit cards now make up 58.4% of all household borrowing. In other words, more and more families are borrowing to meet day-to-day expenses rather than to build assets.
The Final Strike: One Time Settlement (OTS)
The demon was never defeated by cutting off one head after another. Victory came only when the final blow struck him at his core.
Your debt works the same way. Taking new loans to pay old ones is like aiming for the heads: the problem simply grows back. The only way to strike the core of your debt is through a One Time Settlement (OTS).
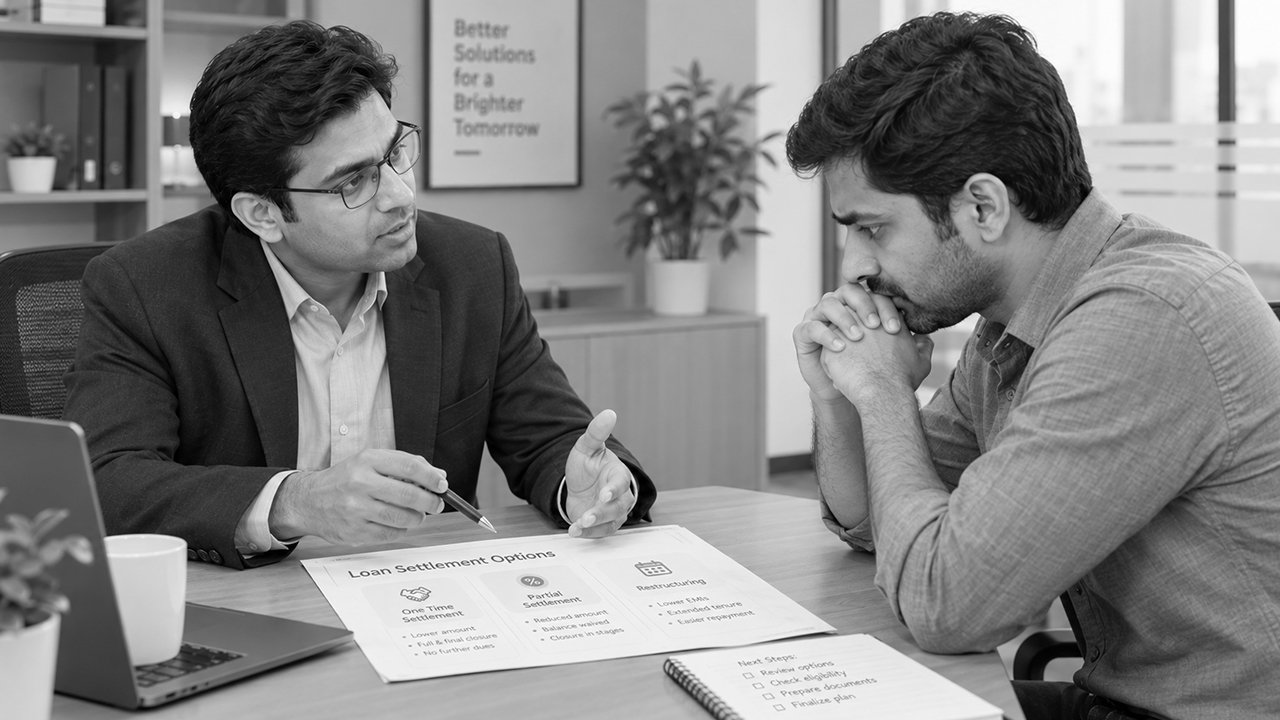
When you face verifiable financial hardship and genuinely cannot repay the inflated loan amount, you have a legal right to opt for a personal loan settlement. In an OTS, the bank agrees to accept a single, lump-sum payment, which is significantly lower than your total outstanding debt, to close the account permanently. Once the payment is made, you receive a No Dues Certificate (NDC), officially ending the debt and the harassment.
How Settle My Loan Fights By Your Side
Fighting powerful banks and aggressive recovery agencies alone can drain your mental health. This is where Settle My Loan (SML) steps in as your strategic partner.
When you enroll in our debt relief program, we take over the battlefield:
- The Legal Shield: Our paralegal team immediately intercepts all creditor communications. We reduce the endless daily calls and prevent unauthorized home visits, giving your family instant peace of mind.
- The Strategic Negotiation: We do not rely on empty promises. Using your genuine financial hardship as our strongest evidence, our legal experts negotiate aggressively with the bank’s core management.
- The Final Victory: We regularly achieve debt reductions of 50% to 70%* for our clients, ensuring the settlement is legally documented and completely binding.
Real-Life Success: Defeating a ₹10.75 Lakh Debt Demon
Sometimes, life throws a “perfect storm” of obstacles at you. Abdul Salim, a 52-year-old resident of Mumbai, faced exactly this. After a sudden job loss and a major accident requiring critical surgeries, his life savings were completely wiped out.
Working as a food delivery partner while recovering, Abdul simply could not pay his unsecured loans, which had ballooned to a terrifying ₹10,75,772. The harassment was brutal. Recovery agents constantly abused his family and even invaded his home, turning his life into a living nightmare.
Desperate for peace, Abdul reached out to Settle My Loan.
- Immediate Protection: Our legal team instantly took over all creditor communications, legally reducing the abusive calls and home visits.
- The Result: We leveraged his severe medical history to build a bulletproof case of “Genuine Financial Hardship,” and aggressively negotiated a One Time Settlement (OTS).
The Final Numbers:
- Total Outstanding Debt: ₹10,75,772
- Settled For: ₹1,86,541
- Net Savings: 83% (₹8.89 Lakhs saved!)
We didn’t just save Abdul money; we bought him the peace he desperately needed to heal physically and mentally. Today, he is completely debt-free.
From medical crisis to saving 83% on debt: Click Here to Read Abdul’s Full Case Study
Conclusion: Burn the Stress, Start Fresh
This Dussehra, as you watch the effigy of Ravana burn to ashes, make a promise to burn your financial stress along with it.
Do not let the demon of debt dictate your family’s future, and do not let recovery agents strip away your dignity. You have the power to change your story. By choosing a legal loan settlement, you can completely eliminate your unmanageable debt and start fresh.
Take the right step today. Connect with the experts at Settle My Loan, defeat your financial demons, and step into a bright, debt-free life.
Happy Dussehra to you and your family!
Disclaimer: *Settlement percentages mentioned are based on past client outcomes and are not guaranteed. Results depend on individual circumstances and lender approval. A settled account may affect your credit score. Participation, timelines and negotiation terms are subject to eligibility, lender approval, and individual case circumstances. Terms and conditions apply.
FAQ
Do Like and Share